Your pension, ISA, investment account and company money, planned together and invested directly, by a former sovereign wealth fund Chief Risk Officer.
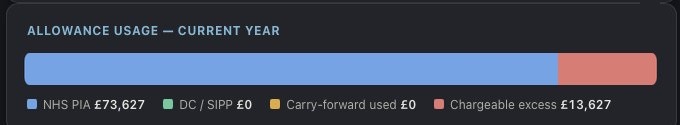
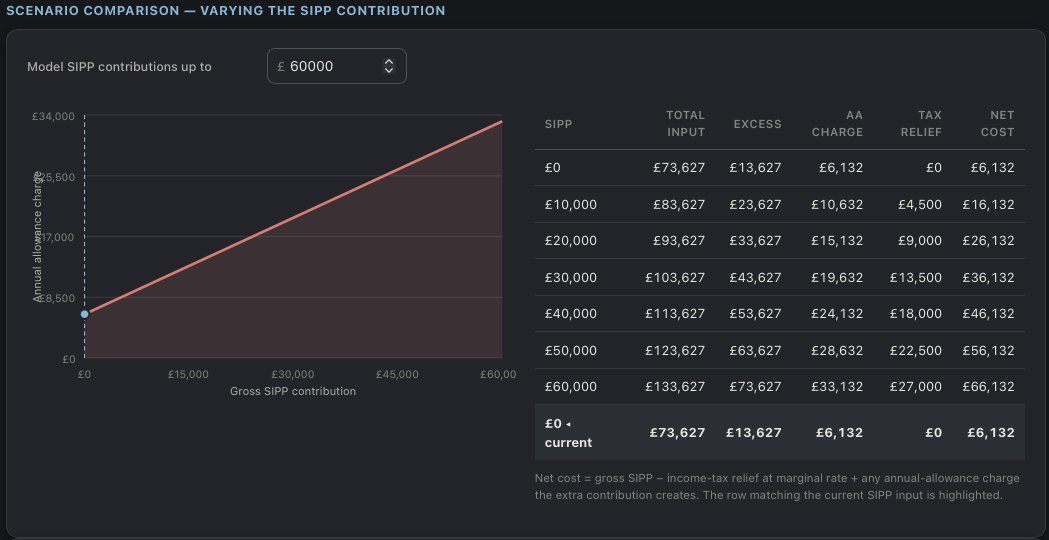
Consultants and GPs earn well and have little time to spare. The NHS pension, the Annual Allowance and private practice income all affect one another, so a decision in one moves the others. We plan them together, invest the money you own directly, and a practising NHS professor sits on our board.
Checks before each tax year ends, using our own NHS Annual Allowance planner.
Whether to trade as a sole trader or through a company, and how to take profits out tax-efficiently.
Old workplace pensions and SIPPs consolidated, with a plan for retirement income and drawdown.
Portfolios of directly held shares, with no managed-fund charges in between.
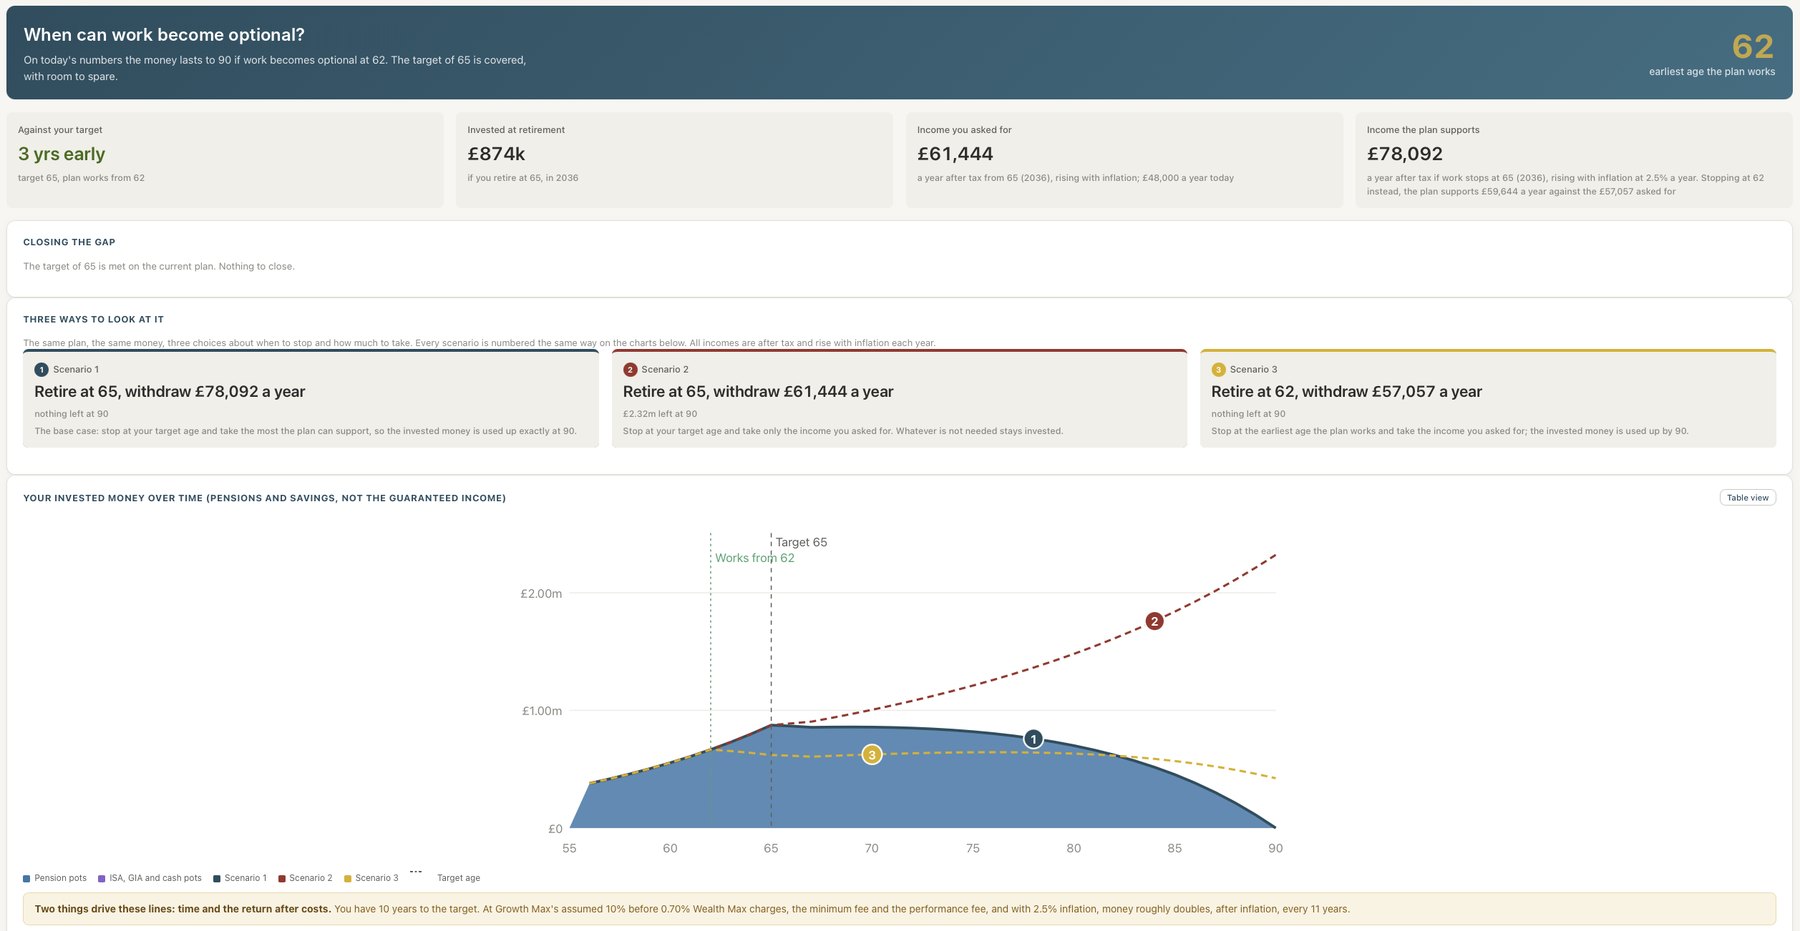
The age at which you could stop working, with the plan tested against market falls of 20% and 40%.
Passing wealth to the next generation with less inheritance tax.
Our board includes Professor Omer Devaja, Professor of Surgery at Maidstone and Tunbridge Wells NHS Trust.
Founders of spin-outs, grant-funded companies and owner-managed businesses face the same three questions: who owns what, where the cash should sit between funding rounds, and what the company is worth to an investor. We answer all three alongside your personal finances.
Holding companies, share classes, shareholder agreements and EMI option schemes.
Salary, dividends and company-funded directors' pensions, planned for tax.

Cash between funding rounds invested to a written mandate, with the company's own risk limits.
Company valuations, financial models, investor decks and readiness packs, and support through a funding round.
Setting up and running a workplace pension.
ISAs, SIPPs and investment accounts held directly, alongside the company.
Former Chief Risk Officer of Kleinwort Benson, Saudi Arabia's Public Investment Fund, where he led the Investment Committee on asset allocation, and Pemberton, now reviewing investor decks from the other side of the table.
For families with interests across South Africa, the Middle East, Europe and the UK, whether local to the region or living there as expatriates. Capital often sits in offshore structures that keep it where it cannot be put to work. A single UK parent company that funds, and receives from, subsidiaries around the world keeps that capital working; offshore structures keep a role for capital that will never need to move.
Group structure built around one parent that funds and receives from subsidiaries in each country.
Surplus capital invested at parent-company level, through a low-cost broker.
Holdings in GBP, EUR and USD, so returns match where the family spends and invests.
Trusts and inheritance planning that work alongside the group structure.
Martin has worked in South Africa, the UK, Luxembourg and Saudi Arabia, where he was the first Chief Risk Officer of the Public Investment Fund. Accounts are held at Interactive Brokers, AJ Bell or Swissquote, including an existing Swissquote account where you already have one.
30 minutes, free, on Teams or by phone.
Your income, assets, goals, attitude to risk and capacity for loss.
Your portfolio and tier set out in writing in a suitability report.
Sign the Client Agreement and open a segregated account with Interactive Brokers, AJ Bell or Swissquote. Wealth Max never holds your money.
Each trade comes to you as a recommendation to approve, and your account is rebalanced to the model portfolio. Log in any time to see it; we review it with you every year and whenever your circumstances change.
Thirty minutes on Teams or by phone, any day with 24 hours' notice. We will tell you honestly whether Wealth Max is the right fit.
Book a 30-minute callCall +44 1622 958990Already spoken to us? Complete your application →